JP Morgan Chief Seeks to Offset UK Bank Tax Increase
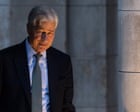
Jamie Dimon announces JP Morgan's strategy to offset Labour's bank tax increase from 3% to 6%, calling it unfair and demonstrating trade-offs.
JP Morgan Chief Seeks to Offset UK Bank Tax Increase
Jamie Dimon, the chief executive of JP Morgan, has stated that his institution will pursue strategic measures to counterbalance the recent JP Morgan bank tax increase implemented by the UK government. During remarks at a London event on Thursday, Dimon characterized the chancellor's decision as fundamentally unfair, signaling the financial services sector's growing concern over heightened regulatory costs.
Details of the Tax Surcharge Increase
The UK government, under Labour's administration, has raised the bank surcharge from 3% to 6%, effectively doubling the tax burden on major financial institutions operating within British markets. This significant adjustment represents one of the most substantial tax policy changes affecting the banking sector in recent years, prompting immediate responses from industry leaders worldwide.
Dimon's comments reflect broader tensions between financial regulators and banking executives regarding the balance between taxation objectives and operational sustainability. The JP Morgan bank tax increase will have considerable implications not only for the multinational institution but also for the entire financial services landscape within the United Kingdom.
Jamie Dimon's Strategic Response
During his Thursday address, the JP Morgan executive emphasized that his organization would actively seek ways to recoup the financial impact of the increased surcharge. Dimon stated he was "setting an example so that governments understand the trade-offs of these unfair penalties," thereby positioning JP Morgan as a vocal advocate challenging the tax adjustment.
His declaration signals that major financial institutions are prepared to implement operational adjustments, potential cost reductions, or strategic repositioning to mitigate the financial consequences of heightened taxation. This approach underscores the competitive dynamics between national governments seeking revenue and multinational banks pursuing profit optimization.
Implications for the Banking Sector
The chancellor's decision to elevate the bank surcharge rise reflects government priorities regarding public revenue generation and wealth redistribution. However, banking executives argue that such measures may inadvertently create economic headwinds, potentially affecting employment levels, investment capabilities, and competitive positioning within global financial markets.
Dimon's public stance demonstrates that industry leaders are willing to engage in transparent dialogue with policymakers regarding taxation consequences. By articulating concerns about fairness and advocating for reconsideration, JP Morgan joins other financial institutions in questioning whether the increased fiscal burden achieves intended policy objectives without generating unintended economic disruptions.
Labour's Tax Policy and Financial Governance
The Labour tax policy banks initiative represents a deliberate policy choice aimed at increasing public revenues from profitable financial sector entities. Government officials argue that such taxation mechanisms ensure major corporations contribute proportionally to public finances, particularly following periods of substantial banking sector profitability.
However, banking leadership perspectives diverge significantly from government rationales. Executives contend that excessive taxation may drive relocation of operations to lower-tax jurisdictions, potentially reducing employment opportunities and tax revenues in the United Kingdom. This fundamental disagreement between governmental objectives and corporate interests continues to shape debates regarding optimal financial sector taxation strategies.
Looking Forward
The coming months will likely reveal specific strategies implemented by JP Morgan and comparable institutions to address the increased tax burden. Whether these measures involve operational restructuring, employment adjustments, or enhanced lobbying efforts remains uncertain, but Dimon's public commitment suggests concrete action will follow his statements.
The situation also raises broader questions about effective corporate taxation in an increasingly globalized financial environment. As multinational institutions possess substantial flexibility in determining operational locations and profit allocation methodologies, policymakers face ongoing challenges in balancing revenue objectives with competitive considerations affecting national economies.